What the calculator checks
- TDSR. All monthly debt repayments, with the new mortgage tested at 4% or your rate if higher, must be within 55% of gross monthly income.
- Loan-to-value. The loan cannot exceed 75% of the price for a first housing loan, 45% for a second or 35% for a third.
- Funds. Your cash and CPF must cover the downpayment and Buyer’s Stamp Duty.
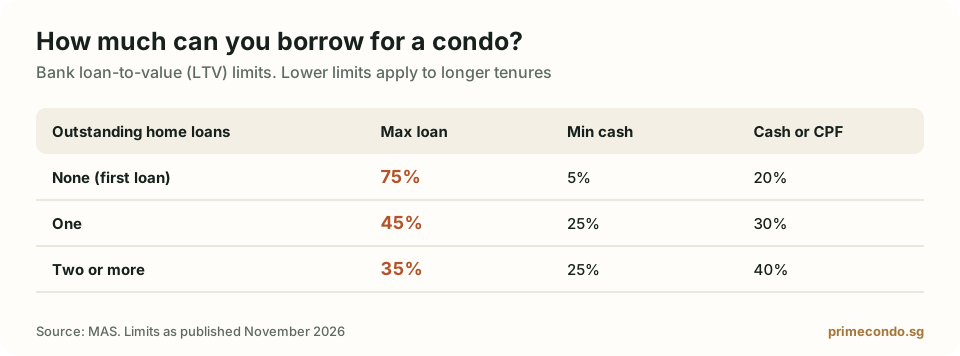
Read How much condo can I afford? for the rules in full, including the lower limits that apply to tenures above 30 years.
Frequently asked questions
What interest rate does the calculator use?
For the TDSR test it uses 4% a year, the minimum stress-test rate banks must apply to residential loans, or your own rate if higher. The estimated actual instalment uses the rate you enter.
Why is my maximum price lower than my loan allows?
Your budget is the lowest of three limits: the loan your income supports under TDSR, the loan-to-value cap, and the cash and CPF you have for the downpayment and stamp duty.
Does it include ABSD?
It includes Buyer’s Stamp Duty and assumes a Singapore Citizen with no ABSD on a first home. If you have one or more existing housing loans, choose that option and add ABSD using the stamp duty calculator.
Rules checked against MAS and IRAS on 10 November 2026. The result assumes the loan ends by age 65 and that at least the minimum cash portion is held in cash. It is an estimate, not a loan offer. A bank’s In-Principle Approval is the only reliable figure.